
Columbus, Ohio, November 20, 2026
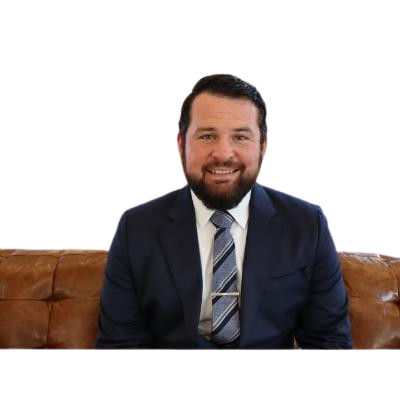
Austyn Thurman discussing Roth conversions
Listen to the interview on the Business Innovators Radio Network: https://businessinnovatorsradio.com/interview-with-austyn-thurman-founder-of-thurman-financial-discussing-roth-conversions/
Roth Conversions Offer Tax-Free Growth
In the realm of retirement planning, the concept of Roth conversions has garnered significant attention for its potential to provide tax-free growth. As individuals seek strategies to optimize their retirement savings, understanding the mechanics and benefits of Roth conversions becomes essential. This essay explores the fundamental aspects of Roth conversions, emphasizing their capacity to facilitate tax-free growth and the strategic advantages they offer in retirement planning.
At its core, a Roth conversion involves transferring funds from a traditional IRA or 401(k) into a Roth IRA. Traditional retirement accounts are typically funded with pre-tax dollars, meaning that taxes on contributions and earnings are deferred until withdrawal. Conversely, Roth IRAs are funded with after-tax dollars, allowing for tax-free growth and tax-free withdrawals in retirement, provided certain conditions are met. The primary allure of a Roth conversion lies in the ability to pay taxes on the converted amount now, rather than during retirement when withdrawals are made.
One of the key benefits of Roth conversions is the development of tax-free retirement income. As highlighted in the podcast discussion with Austin Thurman, the goal of retirement planning is not merely to accumulate the largest possible retirement account but to create a diversified income stream that minimizes tax liabilities. By converting to a Roth IRA, retirees can strategically manage their tax exposure, choosing between taxable and tax-free income sources. This flexibility allows individuals to withdraw funds from their retirement accounts without the burden of additional taxes, thereby preserving their wealth.
Another significant advantage of Roth IRAs is the absence of required minimum distributions (RMDs). Traditional IRAs mandate that account holders begin withdrawing a certain amount from their accounts starting at age 72. These distributions are subject to income tax, which can lead to increased tax liabilities and reduced account balances over time. In contrast, Roth IRAs do not impose such requirements, allowing account holders to retain their funds for longer periods, potentially leading to greater growth and a more substantial legacy for heirs.
Furthermore, Roth conversions can serve as a hedge against future tax increases. As discussed in the podcast, the current economic landscape raises concerns about rising government debt and spending, suggesting that taxes may not decrease in the future as some have predicted. By converting to a Roth IRA, individuals can lock in their current tax rates, protecting themselves from potential increases in tax rates down the line. This foresight can be particularly beneficial for younger individuals or those with a longer investment horizon, as the growth within a Roth IRA is entirely tax-free.
Despite these advantages, it is important to consider the potential drawbacks of Roth conversions. The most immediate consequence is the tax hit incurred during the conversion process. Since taxes must be paid on the converted amount, individuals need to carefully assess their current financial situation and tax bracket before proceeding. However, for many, the long-term benefits of tax-free growth and flexibility can outweigh the short-term costs.
Austyn shared: “The main purpose of a Roth is to try to help you and some of the tax consequences that unfortunately, all of us are subjected to. So that’s in the simplest terms what it is.”
In conclusion, Roth conversions present a compelling strategy for individuals looking to enhance their retirement planning through tax-free growth. By converting traditional retirement accounts into Roth IRAs, individuals can create a diversified income stream, avoid mandatory withdrawals, and protect themselves from future tax increases. While there are initial tax implications to consider, the long-term benefits of tax-free growth and financial flexibility make Roth conversions a valuable option in the pursuit of a secure and prosperous retirement. As with any financial strategy, consulting with a qualified financial advisor is crucial to tailor the approach to individual circumstances and goals.
About Austyn Thurman
Austyn Thurman is the founder of Thurman Financial and a licensed insurance professional. He helps individuals and families understand their options for retirement income, annuities, and life insurance so they can make confident, informed decisions.
Having grown up around the insurance business, Austyn developed an early appreciation for helping families protect what matters most. His career also includes training and coaching 60 to 90 sales professionals annually at a major corporation, an experience that reinforced his belief in the power of education.
Austyn’s approach starts with listening. Before discussing solutions, he seeks to understand each client’s family, goals, and existing plans. He explains the benefits, costs, and risks in plain language, respects what is already working, and gives clients room to make decisions without pressure. When a client’s needs extend beyond his expertise, he helps connect them with the appropriate professionals.
Outside of work, Austyn is a father of four, a football fan, and someone who enjoys a good cigar and a glass of bourbon. Giving back has been part of his life since childhood. Each year, he helps provide 1,000 Christmas toys and 100 Thanksgiving turkeys for families in need, a tradition that remains one of the most meaningful parts of his year.
Learn More: https://www.thurmanfinancial.com/
Recent News & Interviews:
- Austyn Thurman Discussed Estate Planning https://authoritypresswire.com/austyn-thurman-founder-of-thurman-financial-interviewed-on-the-influential-entrepreneurs-podcast-discussing-estate-planning/
The information provided by Thurman Financial is intended for educational and informational purposes only and should not be considered personalized financial, investment, tax, or legal advice.
Financial strategies, including life insurance, retirement planning, wealth preservation, estate planning, and tax-efficient strategies, should be evaluated based on each individual’s unique financial circumstances, goals, and needs. All financial products and strategies involve potential risks, limitations, and costs. Results are not guaranteed, and past performance does not guarantee future results.
Thurman Financial encourages individuals to consult with appropriately licensed financial, tax, and legal professionals before making financial decisions.