
TELFORD, PA, October 7, 2026
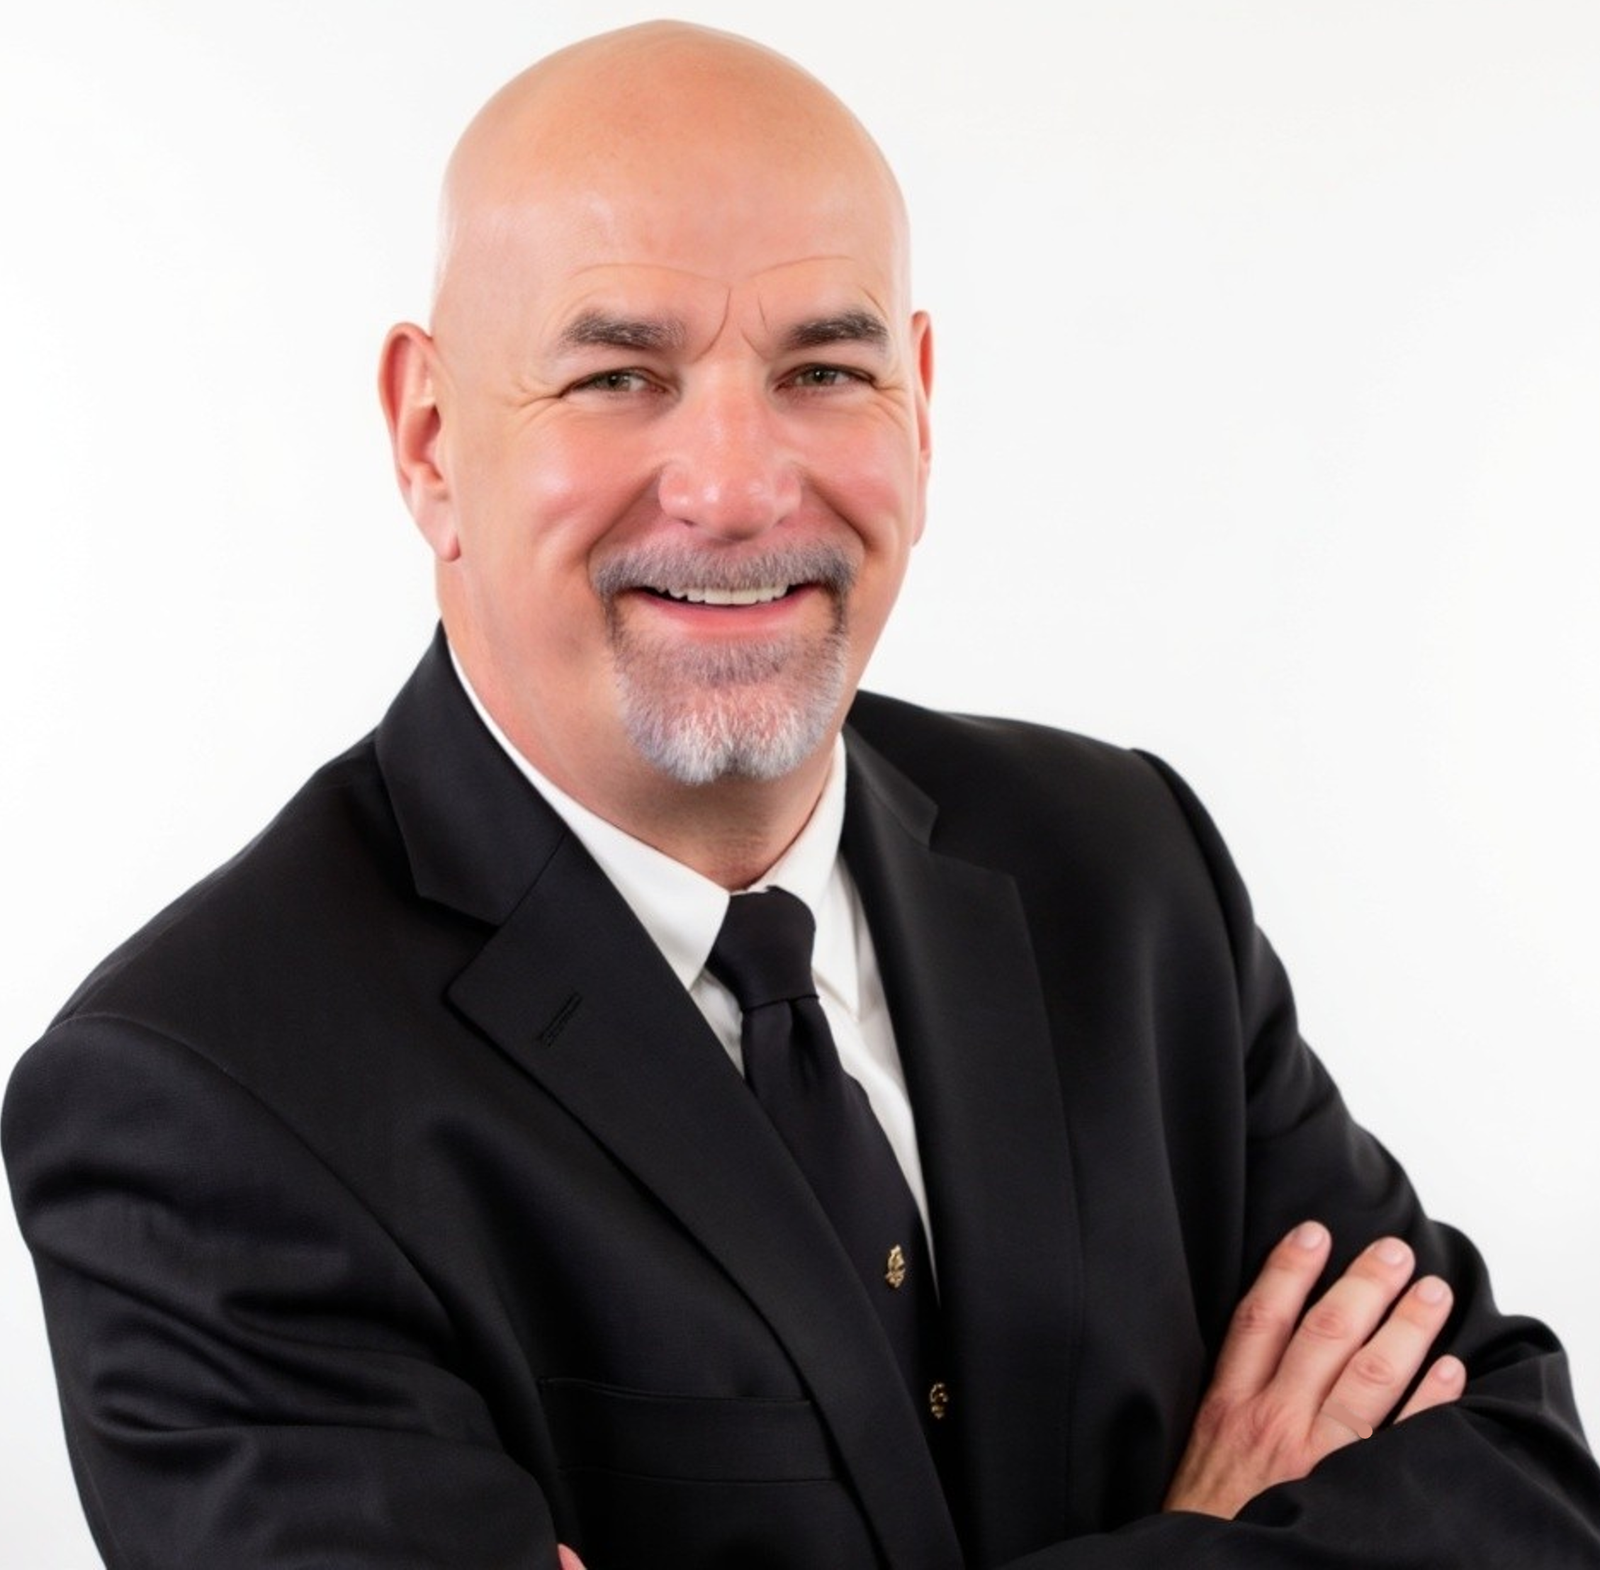
George McReynolds discussing fixing the survivor jaw
Listen to the interview on the Business Innovators Radio Network: https://businessinnovatorsradio.com/interview-with-george-mcreynolds-founder-of-mcreynolds-company-discussing-fixing-the-survivor-jaw/
Planning for Survivor’s Financial Longevity
In today’s world, financial planning for retirement is a critical concern for many individuals, particularly couples. However, a significant aspect often overlooked is the financial longevity of the survivor, typically the spouse left behind after one partner passes away. The podcast episode featuring George McReynolds sheds light on this crucial topic, emphasizing the importance of preparing for the financial realities that arise when one partner dies.
Understanding the Survivor’s Financial Landscape
The survivor’s financial situation is often precarious due to several factors. Most retirement plans are based on averages, which can be misleading. The average life expectancy may not accurately reflect the unique circumstances of each couple. For instance, research from the Social Security Administration indicates that many individuals may live significantly longer than the average, especially women, who statistically outlive men. Consequently, when planning for retirement, it’s essential to consider not just the couple’s joint life expectancy but also the potential for one partner to live an additional 10 to 15 years alone.
One of the primary issues that arise in this context is the reduction in income after the death of one spouse. Many couples opt for single-life annuities, which provide higher payouts during their lifetime but leave the surviving spouse without financial support once the primary earner passes away. Alternatively, a joint and survivor annuity offers lower monthly payments but ensures ongoing income for the surviving spouse. This decision is critical, as it directly impacts the financial stability of the survivor.
The Widow’s Penalty
The concept of the “widow’s penalty” is a significant concern in retirement planning. When one spouse dies, the income typically decreases due to the loss of Social Security benefits and pension income. However, the tax implications do not necessarily decrease at the same rate. For instance, while the survivor may lose one Social Security paycheck, they still face the same required minimum distributions (RMDs) from their retirement accounts, which can push them into higher tax brackets. This situation is exacerbated by the fact that the standard deduction and other tax benefits are often halved for single filers, leading to an increased tax burden during a time when expenses may also rise.
The Importance of Comprehensive Planning
Given these challenges, comprehensive financial planning for both partners is paramount. Couples should engage in discussions about their joint mortality and consider scenarios where one partner may outlive the other. This includes evaluating their retirement income sources, understanding the implications of pension options, and anticipating changes in tax obligations.
Moreover, it is prudent to stress-test financial plans against various longevity scenarios. This means preparing for the possibility that the surviving spouse may need additional funds to cover increased living costs, healthcare expenses, and other unforeseen financial burdens. By proactively planning for the financial longevity of the survivor, couples can mitigate the risks associated with unexpected life events.
In conclusion, planning for survivors’ financial longevity is an essential aspect of retirement planning that cannot be overlooked. The statistics and insights shared by George McReynolds highlight the need for couples to consider the potential financial implications of one partner’s death and to create a robust plan that ensures the surviving spouse is well-supported. By addressing these concerns and preparing for the realities of widowhood, couples can achieve greater peace of mind and financial security in their retirement years. Ultimately, a well-thought-out financial plan not only safeguards the future of the survivor but also honors the shared life and dreams of both partners.
George shared: “Some interesting research from the Social Security Administration, the age of widowhood, when it starts and how long it lasts, it just boggles the mind. So, you can’t just plan on one life expectancy and life expectancy by itself. You have to plan on eventually the plan is going to be for one person.”
About George McReynolds
George McReynolds, CFP® is a veteran wealth manager, tax strategist, and best-selling author who has spent four decades at the intersection of money, taxes, and real-world decision-making.
After leaving public safety in 1985, George entered banking, where his early grounding in tax fundamentals made him a natural fit for working with business owners and affluent borrowers. He became a go-to resource within private banking circles, earning what he describes as a “ringside seat” to how wealthy families actually manage — and mismanage — money.
In 1994, after discovering The Great Boom Ahead by Harry Dent, George returned to school to earn his Certified Financial Planner™ designation. Around the same time, he opened a tax preparation practice and worked inside a high-volume tax firm preparing blue-collar returns under intense time pressure. Then followed a CPA firm serving business owners and high-net-worth families. That experience gave him an unusually broad view of the tax system — from the simplest returns to the most complex.
After passing the CFP® board exam, George was recruited to a prestigious investment firm on Philadelphia’s Main Line. Soon after, he launched a comprehensive financial planning program inside the credit union of a major pharmaceutical company, where he helped more than a thousand pharma employees and retirees navigate retirement, taxes, stock compensation, and benefit decisions.
In 2001, George published his first book, Prosperity by Design, and became an independent advisor. Since then, he has authored or contributed to multiple books, including The Longevity Trap, Defuse the Tax Bomb, Uncle Joe’s Gems, The Pension Shield Option™, Stop, DROP and Roll, Retire Abundantly, and Expert Stories and he wrote the foreword to The New Holistic Retirement, and 9 Money Mistakes Doctors Make.
George has spoken internationally at venues including Oxford University, the Royal Society of Medicine, the London Stock Exchange, the Harvard Club of Boston, and the FBI National Academy Association. He has been featured in CNN, the Financial Times, Yahoo! Finance, Business Insider, and Philadelphia Life magazine.
Defuse the Tax Bomb distills the framework George developed after watching too many successful families lose hundreds of thousands of dollars to taxes they never saw coming — not because they made bad decisions, but because no one showed them how the system actually works over time.
Learn more: https://www.mcwealth.com/
Or buy the book at: https://justabundance.com/
Securities and Advisory Services offered through LPL Financial, registered investment advisor. Member FINRA/SIPC
Recent News & Interviews:
- George McReynolds discussed The Longevity Trap https://authoritypresswire.com/george-mcreynolds-founder-of-mcreynolds-company-interviewed-on-the-influential-entrepreneurs-podcast-discussing-the-longevity-trap/
- George McReynolds discussed Healthcare and Long-term Care https://authoritypresswire.com/george-mcreynolds-founder-of-mcreynolds-company-interviewed-on-the-influential-entrepreneurs-podcast-discussing-healthcare-and-long-term-care/
- George McReynolds discussed Inflation and Safety Jaws https://authoritypresswire.com/george-mcreynolds-founder-of-mcreynolds-company-interviewed-on-the-influential-entrepreneurs-podcast-discussing-inflation-and-safety-jaws/